Keeping your parents’ property tax when you inherit the family home.
Under Proposition 19, a child who inherits a parent’s home may keep the parent’s low property tax value, up to a limit, if the child makes the home their own residence. The benefit is easy to lose. It turns on how the trust is written, how it is administered after the death, and two filing deadlines.
Eligibility depends on the facts of each transfer and is determined by the county assessor. The figures below are an illustration.
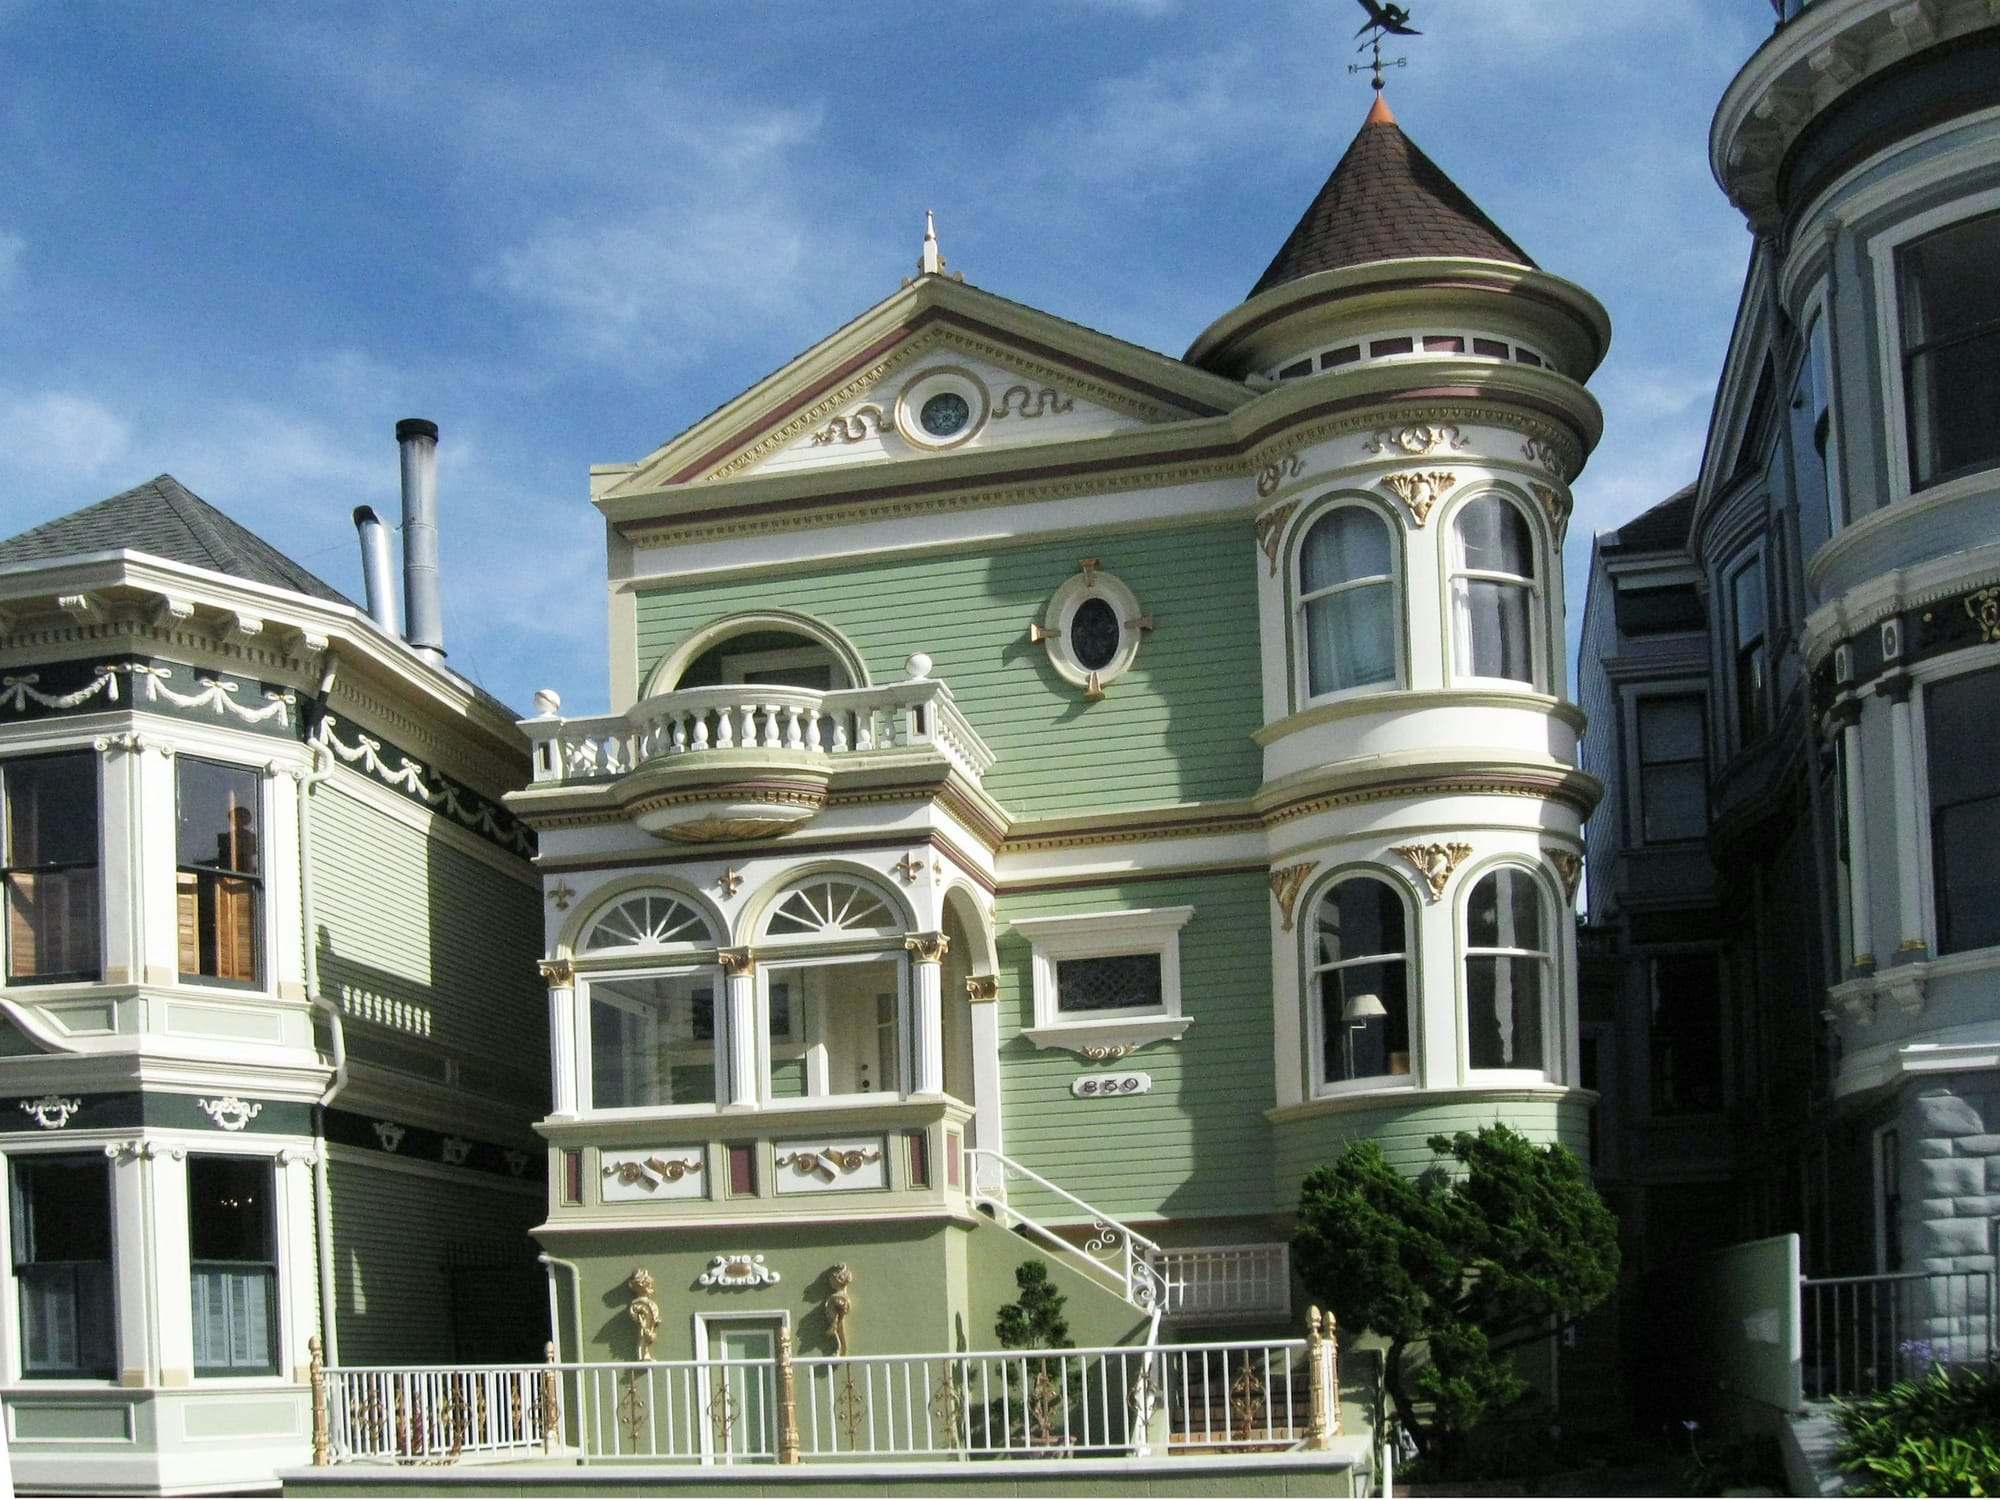
The parents’ home, passed to a child who lives there
Since February 16, 2021, a transfer of a parent’s principal residence to a child is excluded from reassessment if the child makes it the child’s own principal residence within one year. When the transfer is at death, the date of death is the date of transfer, whether the home passes through a trust or a will.
Read moreShow less
The exclusion applies only to the parents’ own home: the dwelling that qualified for the homeowners’ exemption because they owned it and lived in it. Rentals, a vacation home and other real estate are reassessed to their value at the date of death.
The child must file for the homeowners’ exemption within one year and file the claim for the exclusion (form BOE-19-P) with the county assessor within three years, or before any transfer to a third party, whichever comes first.
How the new taxable value is calculated
The exclusion protects the home’s factored base year value, the original purchase price adjusted each year for inflation (never more than 2% a year), plus an allowance that the Board of Equalization adjusts every two years. For transfers from February 16, 2025 through February 15, 2027, the allowance is $1,044,586. Value above that amount is added to the taxable value.
In the example below, the parents bought the home for $100,000, and the second parent dies in 2026.
- Step 1Factored base year valueBy the second death, years of inflation adjustments have brought the original $100,000 to $190,000. This figure appears as the assessed value on the parents’ tax bill, before the homeowners’ exemption.
- Step 2Protected amount$190,000 plus the $1,044,586 allowance equals $1,234,586.
- Step 3ExcessThe home is appraised at $1,800,000. The excess over the protected amount is $565,414.
- Step 4New taxable value$190,000 plus $565,414 equals $755,414. At the 1% general rate, that is about $7,554 a year, compared with about $18,000 on a full reassessment, before local charges.
Common mistakes after the death
- Distributing the house to all of the children and then having one buy out the others: the shares that pass between siblings are reassessed
- Moving out, or renting the home, after the exclusion is granted: from the next January 1 the home is taxed on its date-of-death value, adjusted for inflation, unless another child who inherited moves in within a year
- Holding the home in an LLC or deeding it to one: property held by a legal entity is not eligible
- Missing the one-year homeowners’ exemption deadline or the three-year claim deadline
Trust terms that keep the option open
When one child is likely to keep the family home, the trust should allow it. The Board of Equalization recognizes that the house may be distributed to one child, and other assets to the others, when the house does not exceed that child’s share of the estate. Not every asset has to be divided pro rata.
- Authority to distribute property in kind
- Authority to make non-pro rata distributions
- A specific gift of the residence to a child, where that is the parents’ wish
- Coordination with the parents’ other real estate
- After a spouse’s death, part of a trust often can no longer be amended. Depending on the facts, it may be modified by agreement of the beneficiaries or by a court petition.
If keeping the home in the family matters to you, a restatement of your trust is usually the simplest time to address it.
Administering the trust in the right order
- Step 1Deed to the childThe trustee conveys the home from the trust directly to the child who will live there, rather than to all of the children.
- Step 2Move inThe child makes the home their principal residence within one year of the death.
- Step 3Homeowners’ exemptionThe child files for the homeowners’ exemption within one year.
- Step 4Prop 19 claimThe child files form BOE-19-P within three years, and before any sale to a third party.
My parents lived in one unit of a triplex. Is the whole building protected?
No. Each unit of a multi-unit building is treated as a separate residence. Only the unit your parents lived in can qualify, and it must become your home. The other units are reassessed, even if a sibling moves into one of them.
What about a house with an ADU?
A single-family home with an accessory dwelling unit qualifies for only one homeowners’ exemption, and the Board of Equalization treats it as one residence. The child may live in either the house or the ADU, subject to the conditions in the Board’s rule. An ADU on its own parcel is treated differently.
Two of us inherit, and only one will live there. Is that enough?
Yes. One eligible child living in the home is enough, and the exclusion applies to what each child received from the parents. The child who lives there must be one who inherited from the parents.
What happens if I move out and rent the home later?
The exclusion ends. From the next January 1, the home is taxed on its value at the date of death, adjusted for inflation. Another child who also inherited may keep the exclusion by moving in within one year.
My parent lived in a care facility before death. Does the home still qualify?
It may. A parent confined to a care facility is treated as occupying the home if the parent would otherwise live there, intended to return, and the home was not rented to anyone other than immediate family.
Does Proposition 19 change the income-tax basis?
No. The property tax value and the income-tax basis are separate. For income tax purposes, an inherited home generally receives a basis equal to its value at the date of death, whether or not the property tax exclusion applies.
The trustee has not distributed the house yet. Do the deadlines still run?
The child must still move in within one year of the death. The claim can be accepted as timely in some cases after the three-year period, but waiting is a risk best avoided.
Sources: California State Board of Equalization Publication 801 (June 2025) and Letter To Assessors No. 2026/026 (August 3, 2026).
You may also find helpful
Planning for the family home?
Meetings are by appointment, weekdays 9:30 AM – 5:00 PM, by Zoom or at our offices. Call 888.380.2288 or 415.693.8882, or request a time online. Consultations in English, Cantonese or Mandarin.